HMRC mileage rates have changed twice in 2026, with a further increase announced for April 2027.
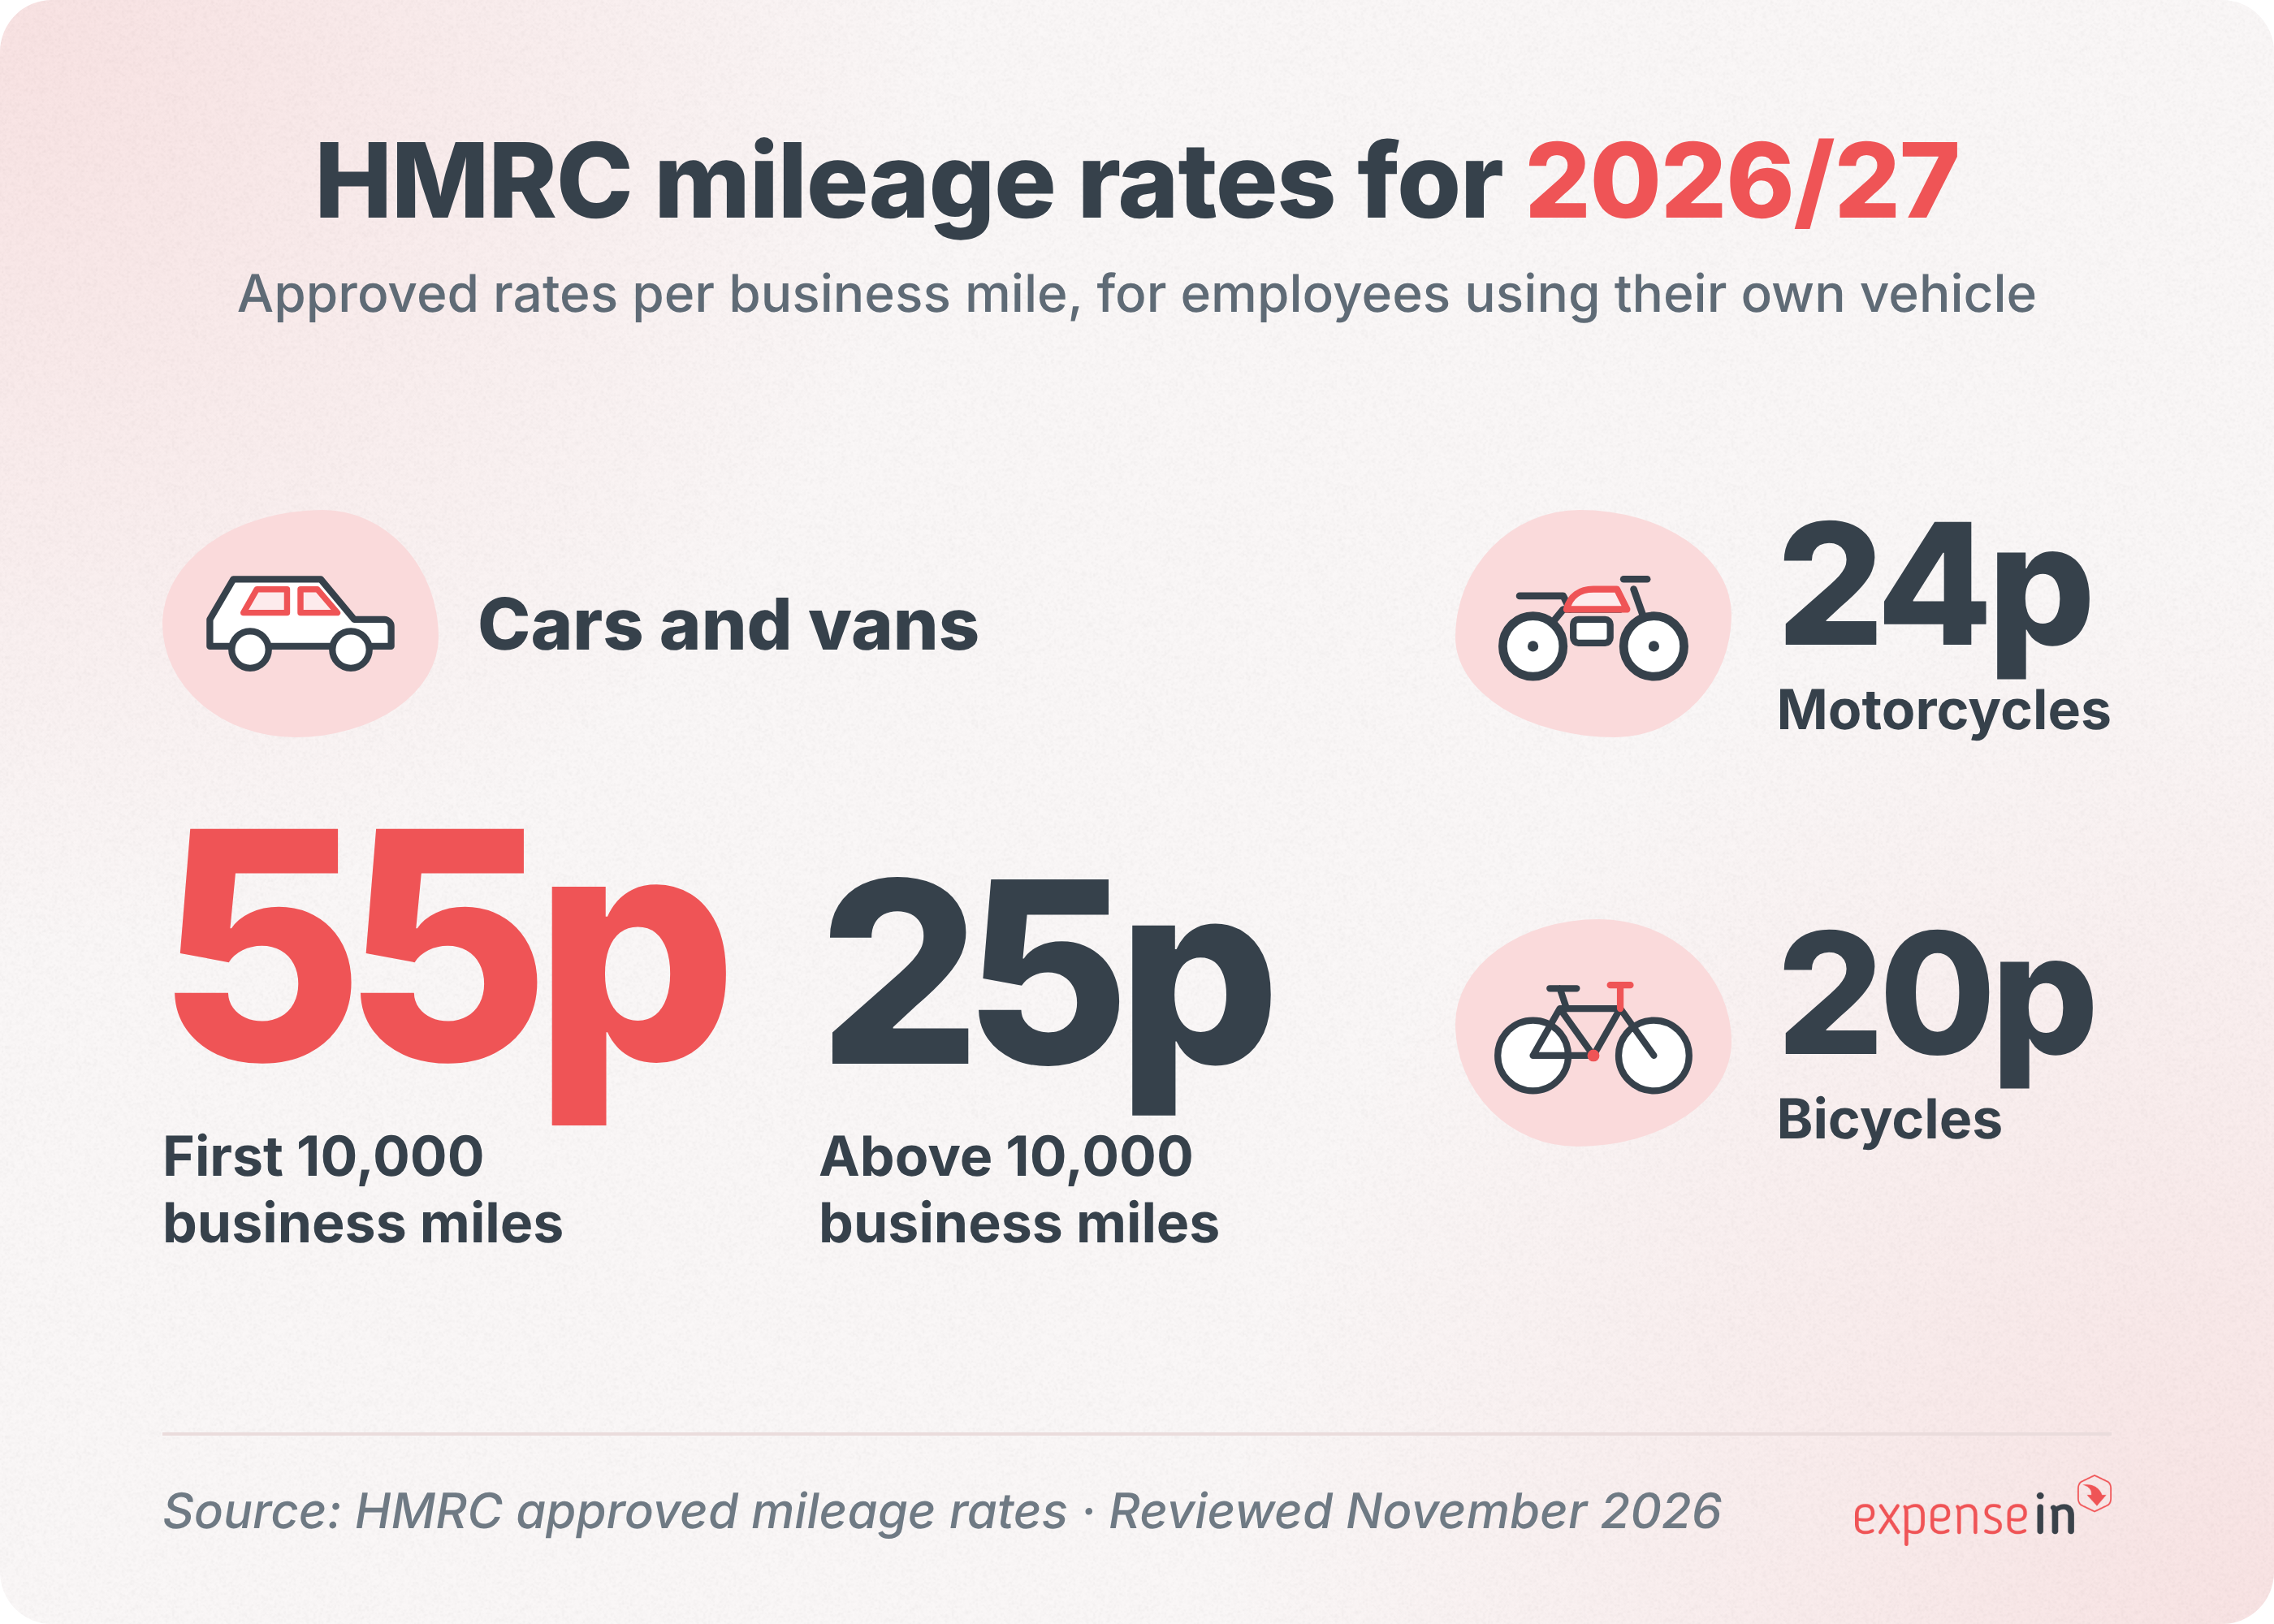
For the 2026/27 tax year, the approved mileage allowance for employees using their own cars or vans is 55p per mile for the first 10,000 business miles, then 25p per mile thereafter. From 6 April 2027, the government plans to increase the rate above 10,000 miles to 35p.
That's good news for employees who regularly travel for work. But for finance teams, it also means checking that reimbursement policies, mileage calculations, and payroll processes reflect the correct rules.
Here's what you need to know about the current HMRC mileage rates, the changes announced in Budget 2026, and how to manage business mileage claims correctly.
What are the current HMRC mileage rates for 2026/27?
HMRC sets approved mileage allowance rates for employees who use their own vehicles for qualifying business journeys.
These rates determine how much an employer can reimburse employees tax-free under the Approved Mileage Allowance Payments (AMAPs) scheme.
The rates depend on the type of vehicle and, for cars and vans, the number of business miles travelled during the tax year.
HMRC mileage rates: 2026/27
Vehicle type | First 10,000 business miles | Miles above 10,000 |
|---|
Cars and vans | 55p per mile | 25p per mile |
Motorcycles | 24p per mile | 24p per mile |
Bicycles | 20p per mile | 20p per mile |
These rates apply from 6 April 2026 to 5 April 2027.
The 10,000-mile threshold applies to qualifying business mileage, not an employee's total annual driving.
For example, if someone drives 15,000 miles during the tax year but only 4,000 are for business purposes, the approved mileage calculation is based on those 4,000 business miles.
The threshold also operates across vehicles of the same category. If an employee uses both their own car and van for work, the qualifying business mileage is combined when calculating the 10,000-mile threshold.
It's worth remembering that HMRC's approved rates are not mandatory employer reimbursement rates. Businesses can choose to pay employees less, although this may allow employees to claim tax relief on the difference.
What's changing following Budget 2026?
The government has announced a further increase to approved mileage rates, following the rise introduced in April 2026.
There are two important changes to understand.
1. The 55p rate for the first 10,000 miles is being made permanent.
From 6 April 2026, the approved rate increased from 45p to 55p per mile for the first 10,000 business miles in an employee's own car or van.
Budget 2026 confirmed that the higher rate will continue beyond the 2026/27 tax year.
2. The rate for mileage above 10,000 miles will increase to 35p.
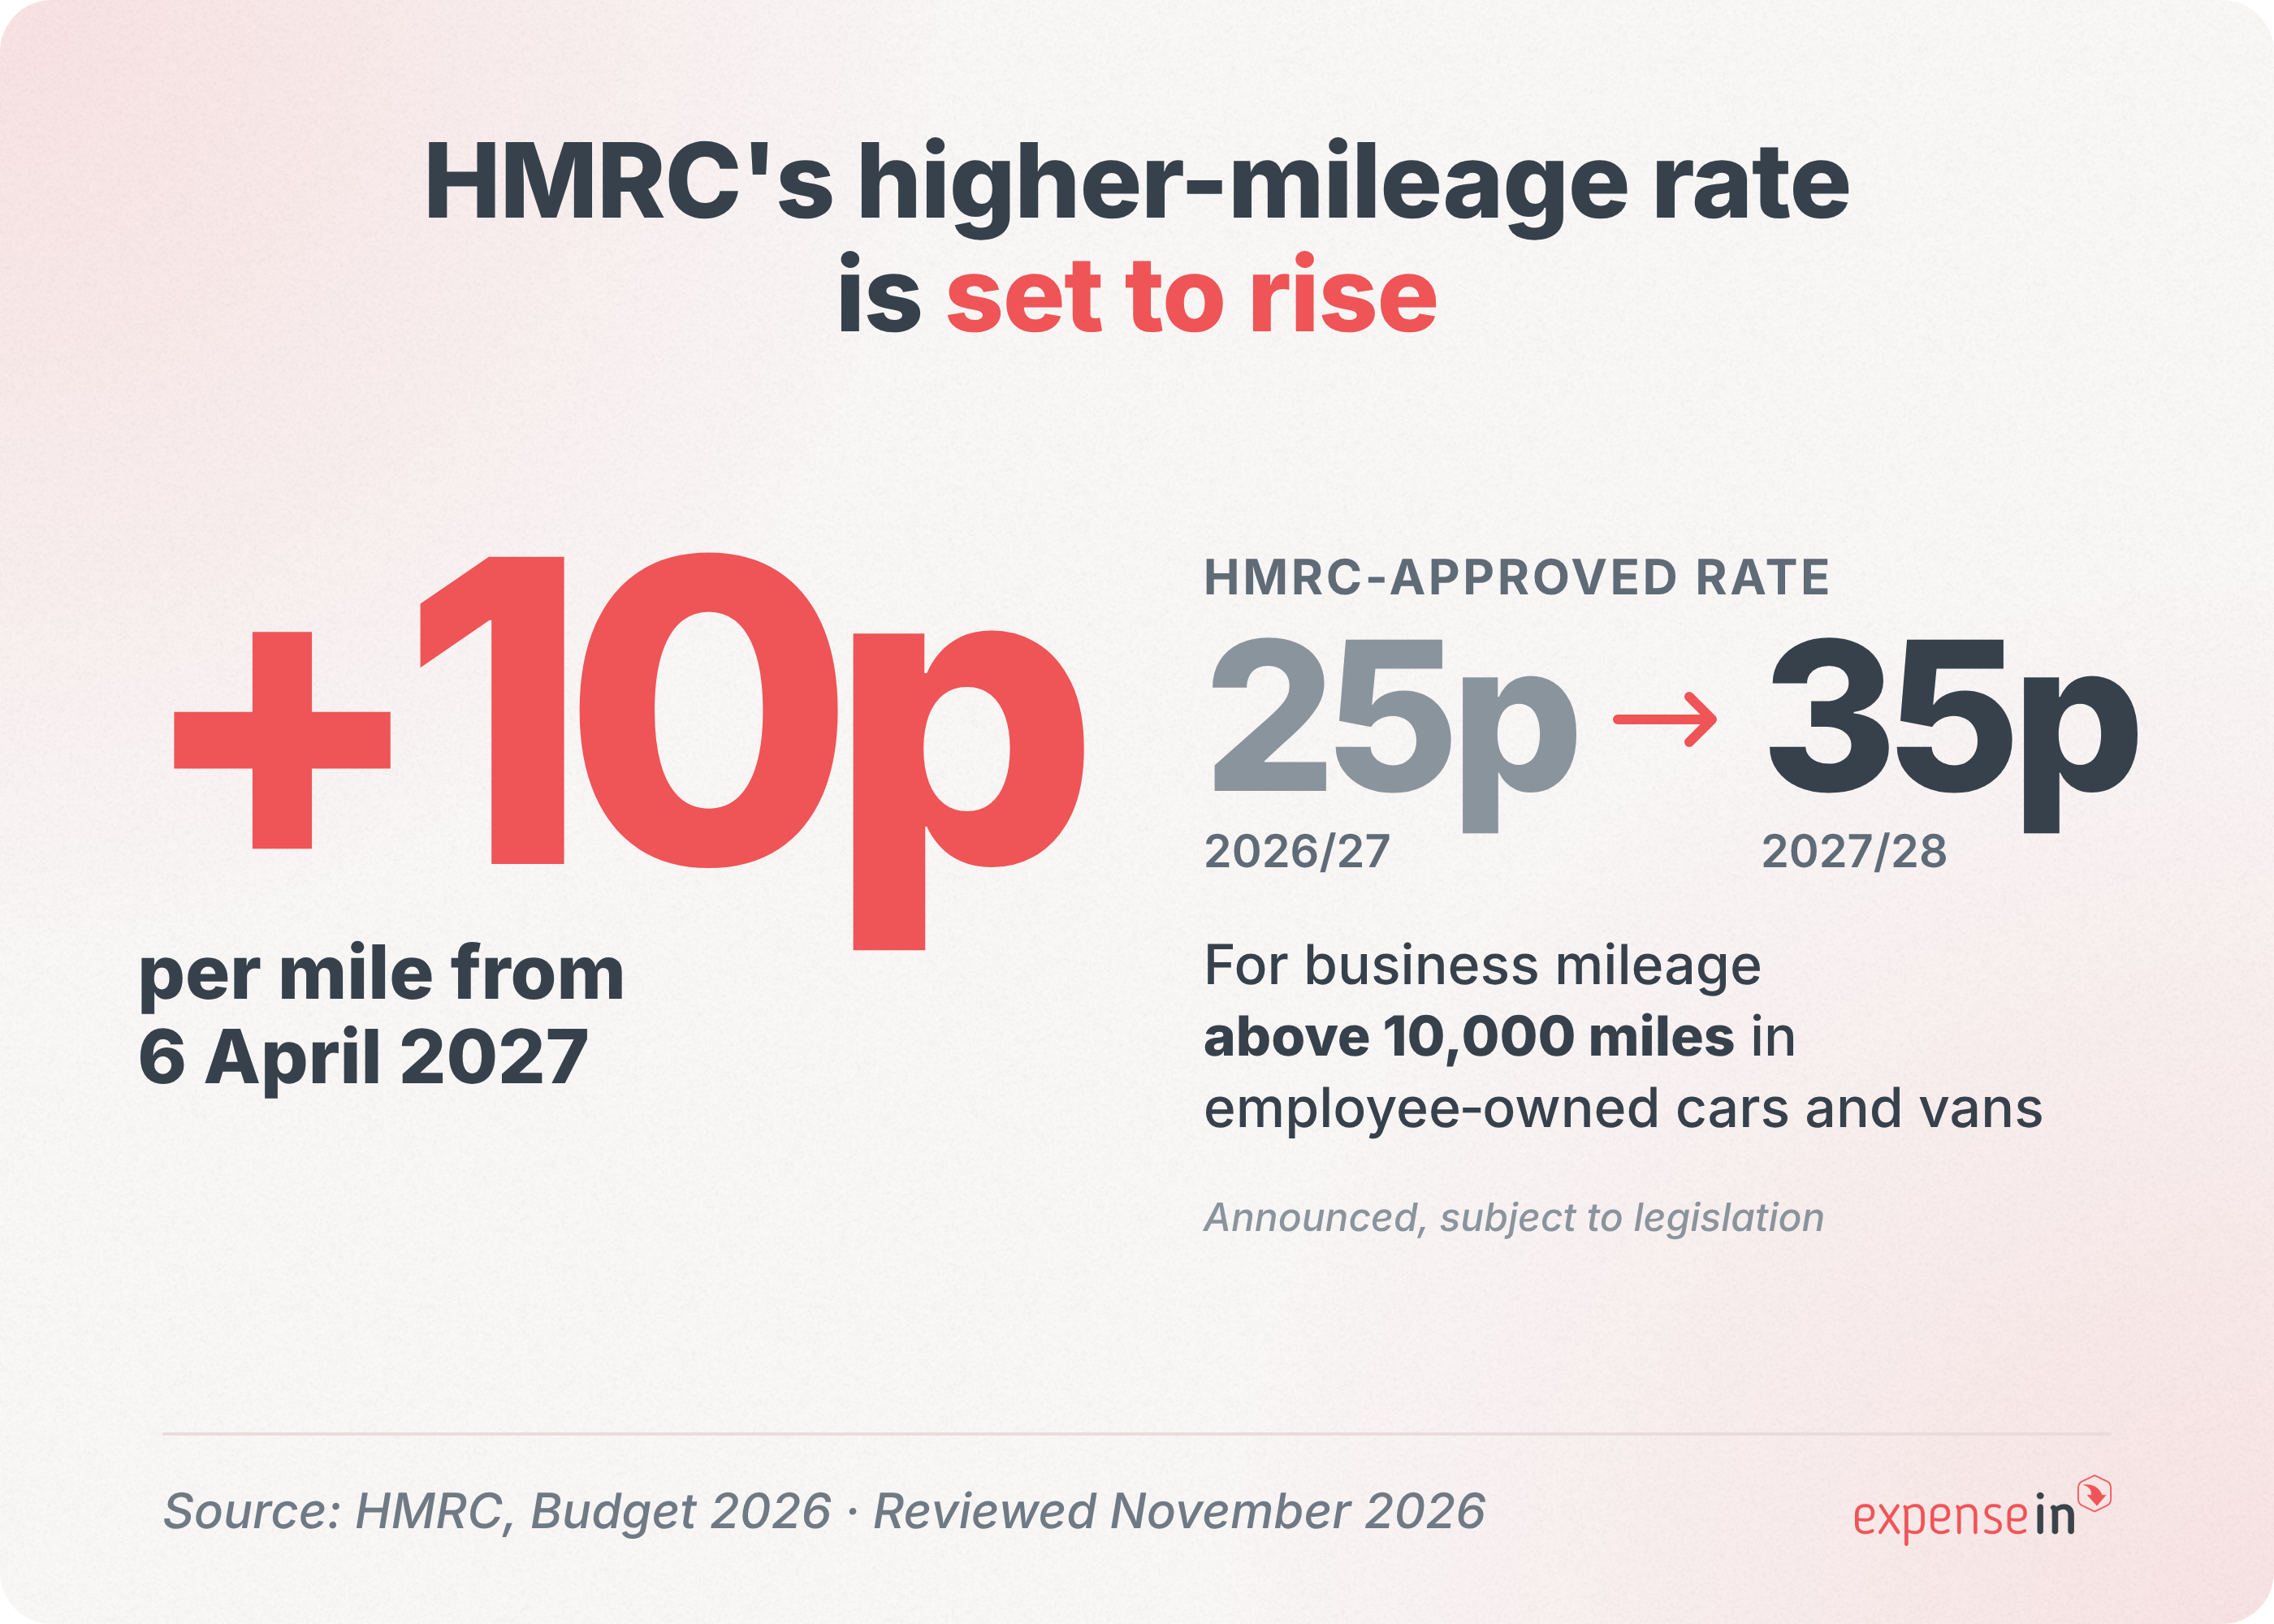
From 6 April 2027, the government plans to increase the approved rate for business mileage above 10,000 miles from 25p to 35p.
The changes will also apply to the corresponding simplified mileage rates for eligible self-employed people.
HMRC mileage rates: 2025/26 vs 2026/27 vs 2027/28
Tax year | First 10,000 business miles | Miles above 10,000 |
|---|
2025/26 | 45p | 25p |
2026/27 | 55p | 25p |
2027/28 (announced) | 55p | 35p |
Rates shown are for cars and vans. As of 19 November 2026, the April 2027 changes have been announced but require implementing legislation.
For finance teams, the distinction matters. The 35p rate does not apply to mileage claims made under the current 2026/27 rules.
The government's Budget documentation confirms the planned effective date of 6 April 2027.
How much can employees claim using HMRC mileage rates?
The calculation is straightforward until someone crosses the 10,000-mile threshold.
For employees driving their own cars or vans, the approved amount is calculated using the number of qualifying business miles in the tax year.
Example: An employee driving 12,000 business miles
Let's say an employee drives 12,000 qualifying business miles in their own car during 2026/27.
Their approved mileage allowance would be:
Calculation | Amount |
|---|
First 10,000 miles × 55p | £5,500 |
Remaining 2,000 miles × 25p | £500 |
Total approved amount | £6,000 |
If they drive the same distance in 2027/28, the announced rates would produce a different result:
Calculation | Amount |
|---|
First 10,000 miles × 55p | £5,500 |
Remaining 2,000 miles × 35p | £700 |
Total approved amount | £6,200 |
That's an additional £200 in potential tax-free mileage reimbursement for an employee covering 12,000 qualifying business miles, assuming the employer chooses to pay the full approved amount.
For employees who travel fewer than 10,000 business miles annually, the announced 2027 increase would not change their approved car or van mileage allowance.
What does the 10,000-mile threshold mean for employers?
The threshold resets at the start of each tax year, on 6 April.
This means mileage calculations need to account for an employee's cumulative business mileage throughout the year, rather than treating every individual claim in isolation.
For example, an employee might submit several expense claims each month. If they've already completed 9,800 business miles, their next claim for 500 miles crosses the threshold.
Under the current 2026/27 rates, that claim would need to be split:
First 200 miles at 55p = £110
Remaining 300 miles at 25p = £75
Total approved amount = £185
Applying 55p to the entire journey would exceed the approved amount for those miles.
For finance teams dealing with frequent mileage claims, maintaining an accurate running total is essential.
What do HMRC mileage allowances actually cover?
One common misconception is that HMRC mileage rates are simply fuel reimbursement rates.
They're not.
Approved Mileage Allowance Payments are designed to cover the wider costs of owning and running a personal vehicle for business use, including:
Petrol, diesel, or electricity
Vehicle servicing, maintenance, and repairs
Tyres and other running costs
Vehicle insurance
Vehicle tax
Depreciation
Employees receiving mileage allowances generally cannot claim additional tax relief for these vehicle-related running costs.
However, certain expenses directly associated with a qualifying business journey may be reimbursed separately.
These can include parking charges and road tolls, subject to the normal rules for allowable business expenses.
For example, an employee travelling to a client meeting could potentially claim both their qualifying business mileage and the cost of parking at the client's premises.
The parking cost isn't included within the approved mileage rate.
Which journeys qualify for business mileage?
Not every journey made during the working day qualifies for tax-free mileage reimbursement.
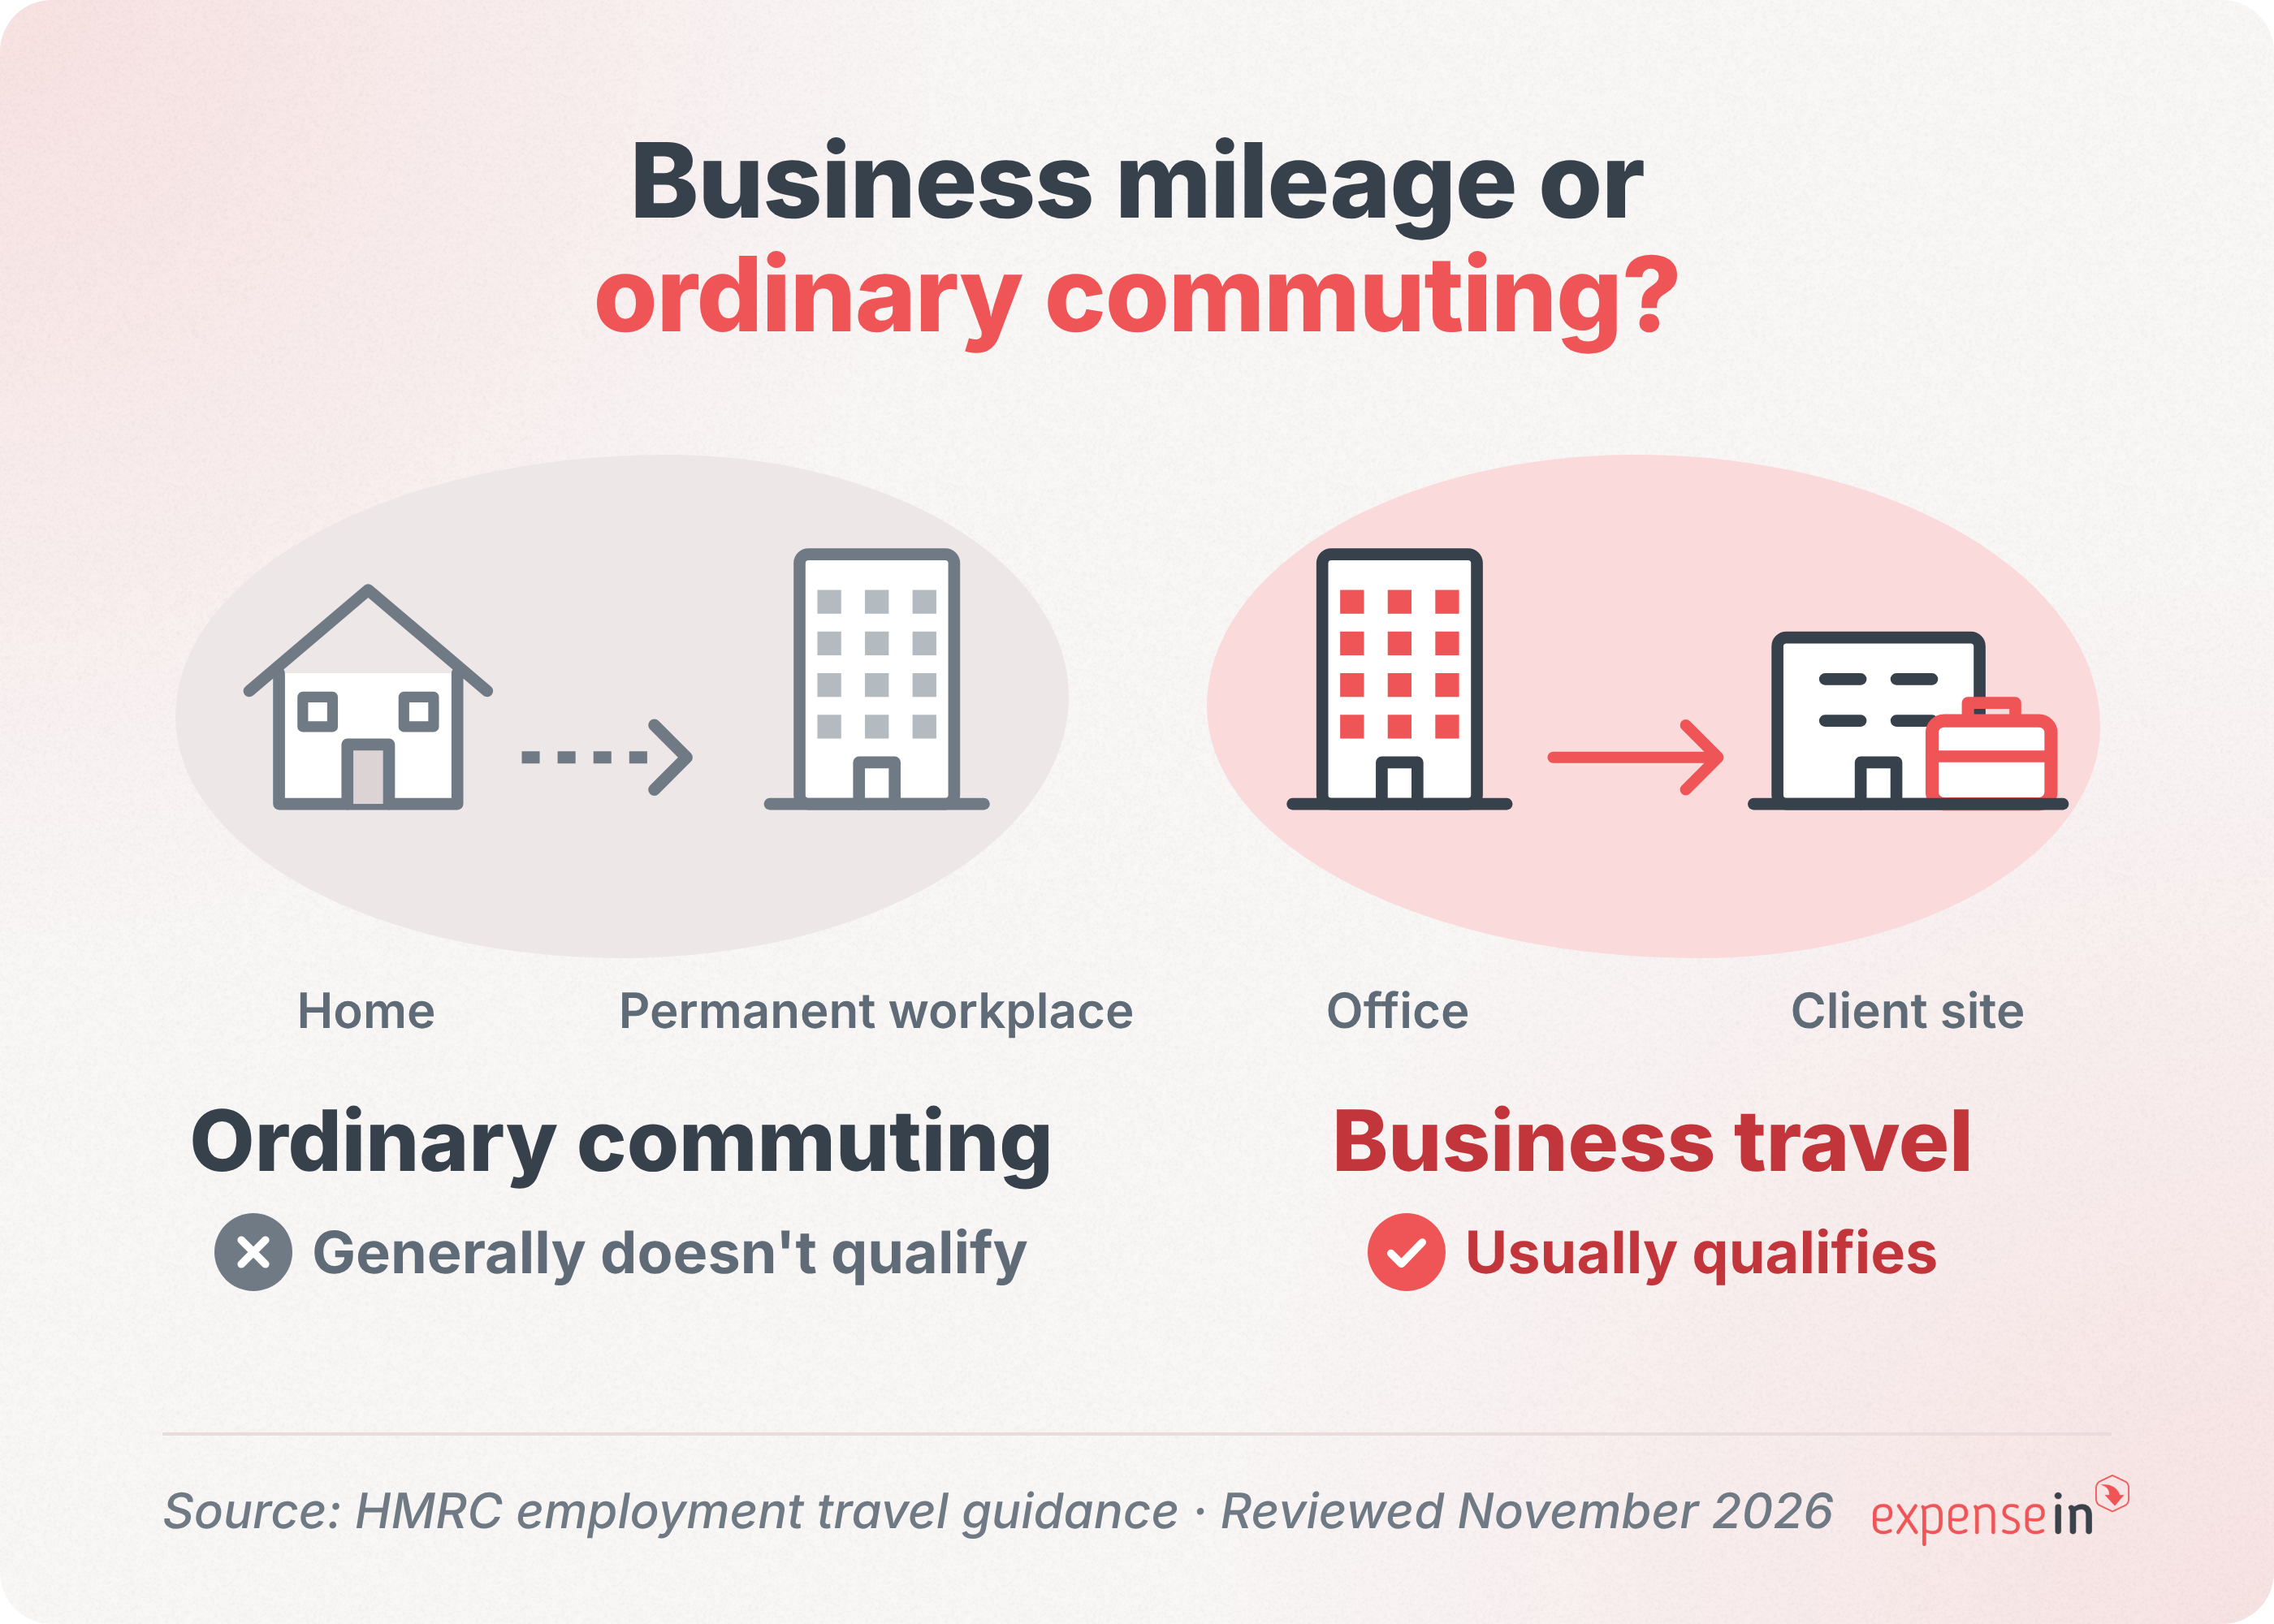
The important distinction is between business travel and ordinary commuting.
HMRC generally allows relief for qualifying journeys undertaken in the performance of an employee's duties, including travel to temporary workplaces.
Examples of qualifying business travel
Depending on the circumstances, eligible journeys can include:
Travelling between different workplaces as part of an employee's duties
Visiting a client or supplier at a temporary location
Attending an off-site business meeting
Travelling to a temporary workplace for a short-term project
What doesn't normally qualify?
Travel between an employee's home and their permanent workplace is generally considered ordinary commuting.
This remains the case even if the employee occasionally works from home or travels outside normal office hours.
For example, an employee who normally works at a permanent office in Manchester cannot typically claim mileage for driving between their home and that office.
However, if they're required to visit a qualifying temporary workplace for a client project, that journey may be eligible.
What is HMRC's 24-month rule?
A temporary workplace doesn't necessarily stay temporary indefinitely.
HMRC's 24-month rule generally prevents a workplace from being treated as temporary where an employee spends at least 40% of their working time there over a period expected to last more than 24 months.
The expectation matters, not just how long the employee eventually stays.
For example, if an employee is assigned to work at another office for 18 months, it may qualify as a temporary workplace.
But if the assignment is later extended beyond 24 months, the tax treatment may change from the point at which the longer assignment becomes expected.
There are additional rules and exceptions, so employers should assess individual working arrangements rather than relying on a blanket policy.
Are HMRC mileage allowances taxable?
Mileage payments within HMRC's approved limits are generally exempt from Income Tax, provided they relate to qualifying business mileage and meet the scheme's conditions.
But when an employer pays above those limits, the excess can become taxable.
There's also an important distinction between Income Tax and National Insurance that finance teams need to understand.
Income Tax: Based on the annual approved amount
For Income Tax purposes, the approved mileage amount is calculated across the tax year.
During 2026/27, that means:
If an employer pays more than the approved amount, the excess is taxable and must be handled under the appropriate HMRC reporting or payroll arrangements.
National Insurance: A different calculation
National Insurance has separate rules for mileage payments and other relevant motoring expenditure.
For 2026/27, the National Insurance qualifying amount for cars and vans is calculated at 55p per business mile, without the 10,000-mile reduction used for Income Tax.
It is also calculated by earnings period rather than using the same annual calculation as Income Tax.
This means a mileage payment can exceed the Income Tax approved amount without automatically creating an equivalent National Insurance liability.
For example, consider an employee who drives 12,000 business miles and receives 55p per mile for every mile.
The employee receives £6,600 in mileage payments, but the approved amount for Income Tax purposes is £6,000.
That creates £600 of taxable mileage payments.
However, that £600 is not automatically subject to National Insurance in the same way. The National Insurance position depends on the qualifying amount and relevant motoring expenditure in each earnings period.
For finance teams, the takeaway is simple: don't use the Income Tax calculation as a substitute for the National Insurance calculation.
The government has also announced that the April 2027 changes will affect the corresponding National Insurance disregard.
Employers should check the implementing regulations and updated HMRC guidance before configuring next year's payroll treatment.
What happens if an employer pays less than the HMRC mileage rate?
Employers don't have to reimburse employees at HMRC's full approved rate.
Some businesses set their own reimbursement rates based on their travel policy and budgets.
However, employees who receive less than the approved amount may be eligible to claim Mileage Allowance Relief (MAR) on the difference.
Example: Claiming Mileage Allowance Relief
An employee drives 4,000 qualifying business miles in their own car during 2026/27.
Their employer reimburses them at 30p per mile.
Calculation | Amount |
|---|
HMRC approved amount: 4,000 × 55p | £2,200 |
Employer reimbursement: 4,000 × 30p | £1,200 |
Potential amount eligible for tax relief | £1,000 |
Importantly, the employee doesn't receive £1,000 back from HMRC.
Mileage Allowance Relief is Income Tax relief on the shortfall, so the actual tax saving depends on the employee's individual circumstances and applicable tax rate.
Eligible employees can claim through HMRC's employment expenses process or Self Assessment, depending on their circumstances.
For employers, clear communication matters. Employees should understand the rate the business pays and how that differs from HMRC's approved amount.
What are the HMRC mileage rates for electric cars?
The mileage rules for electric vehicles depend on who owns the vehicle.
This is one of the most important distinctions to get right.
Employees using their own electric cars
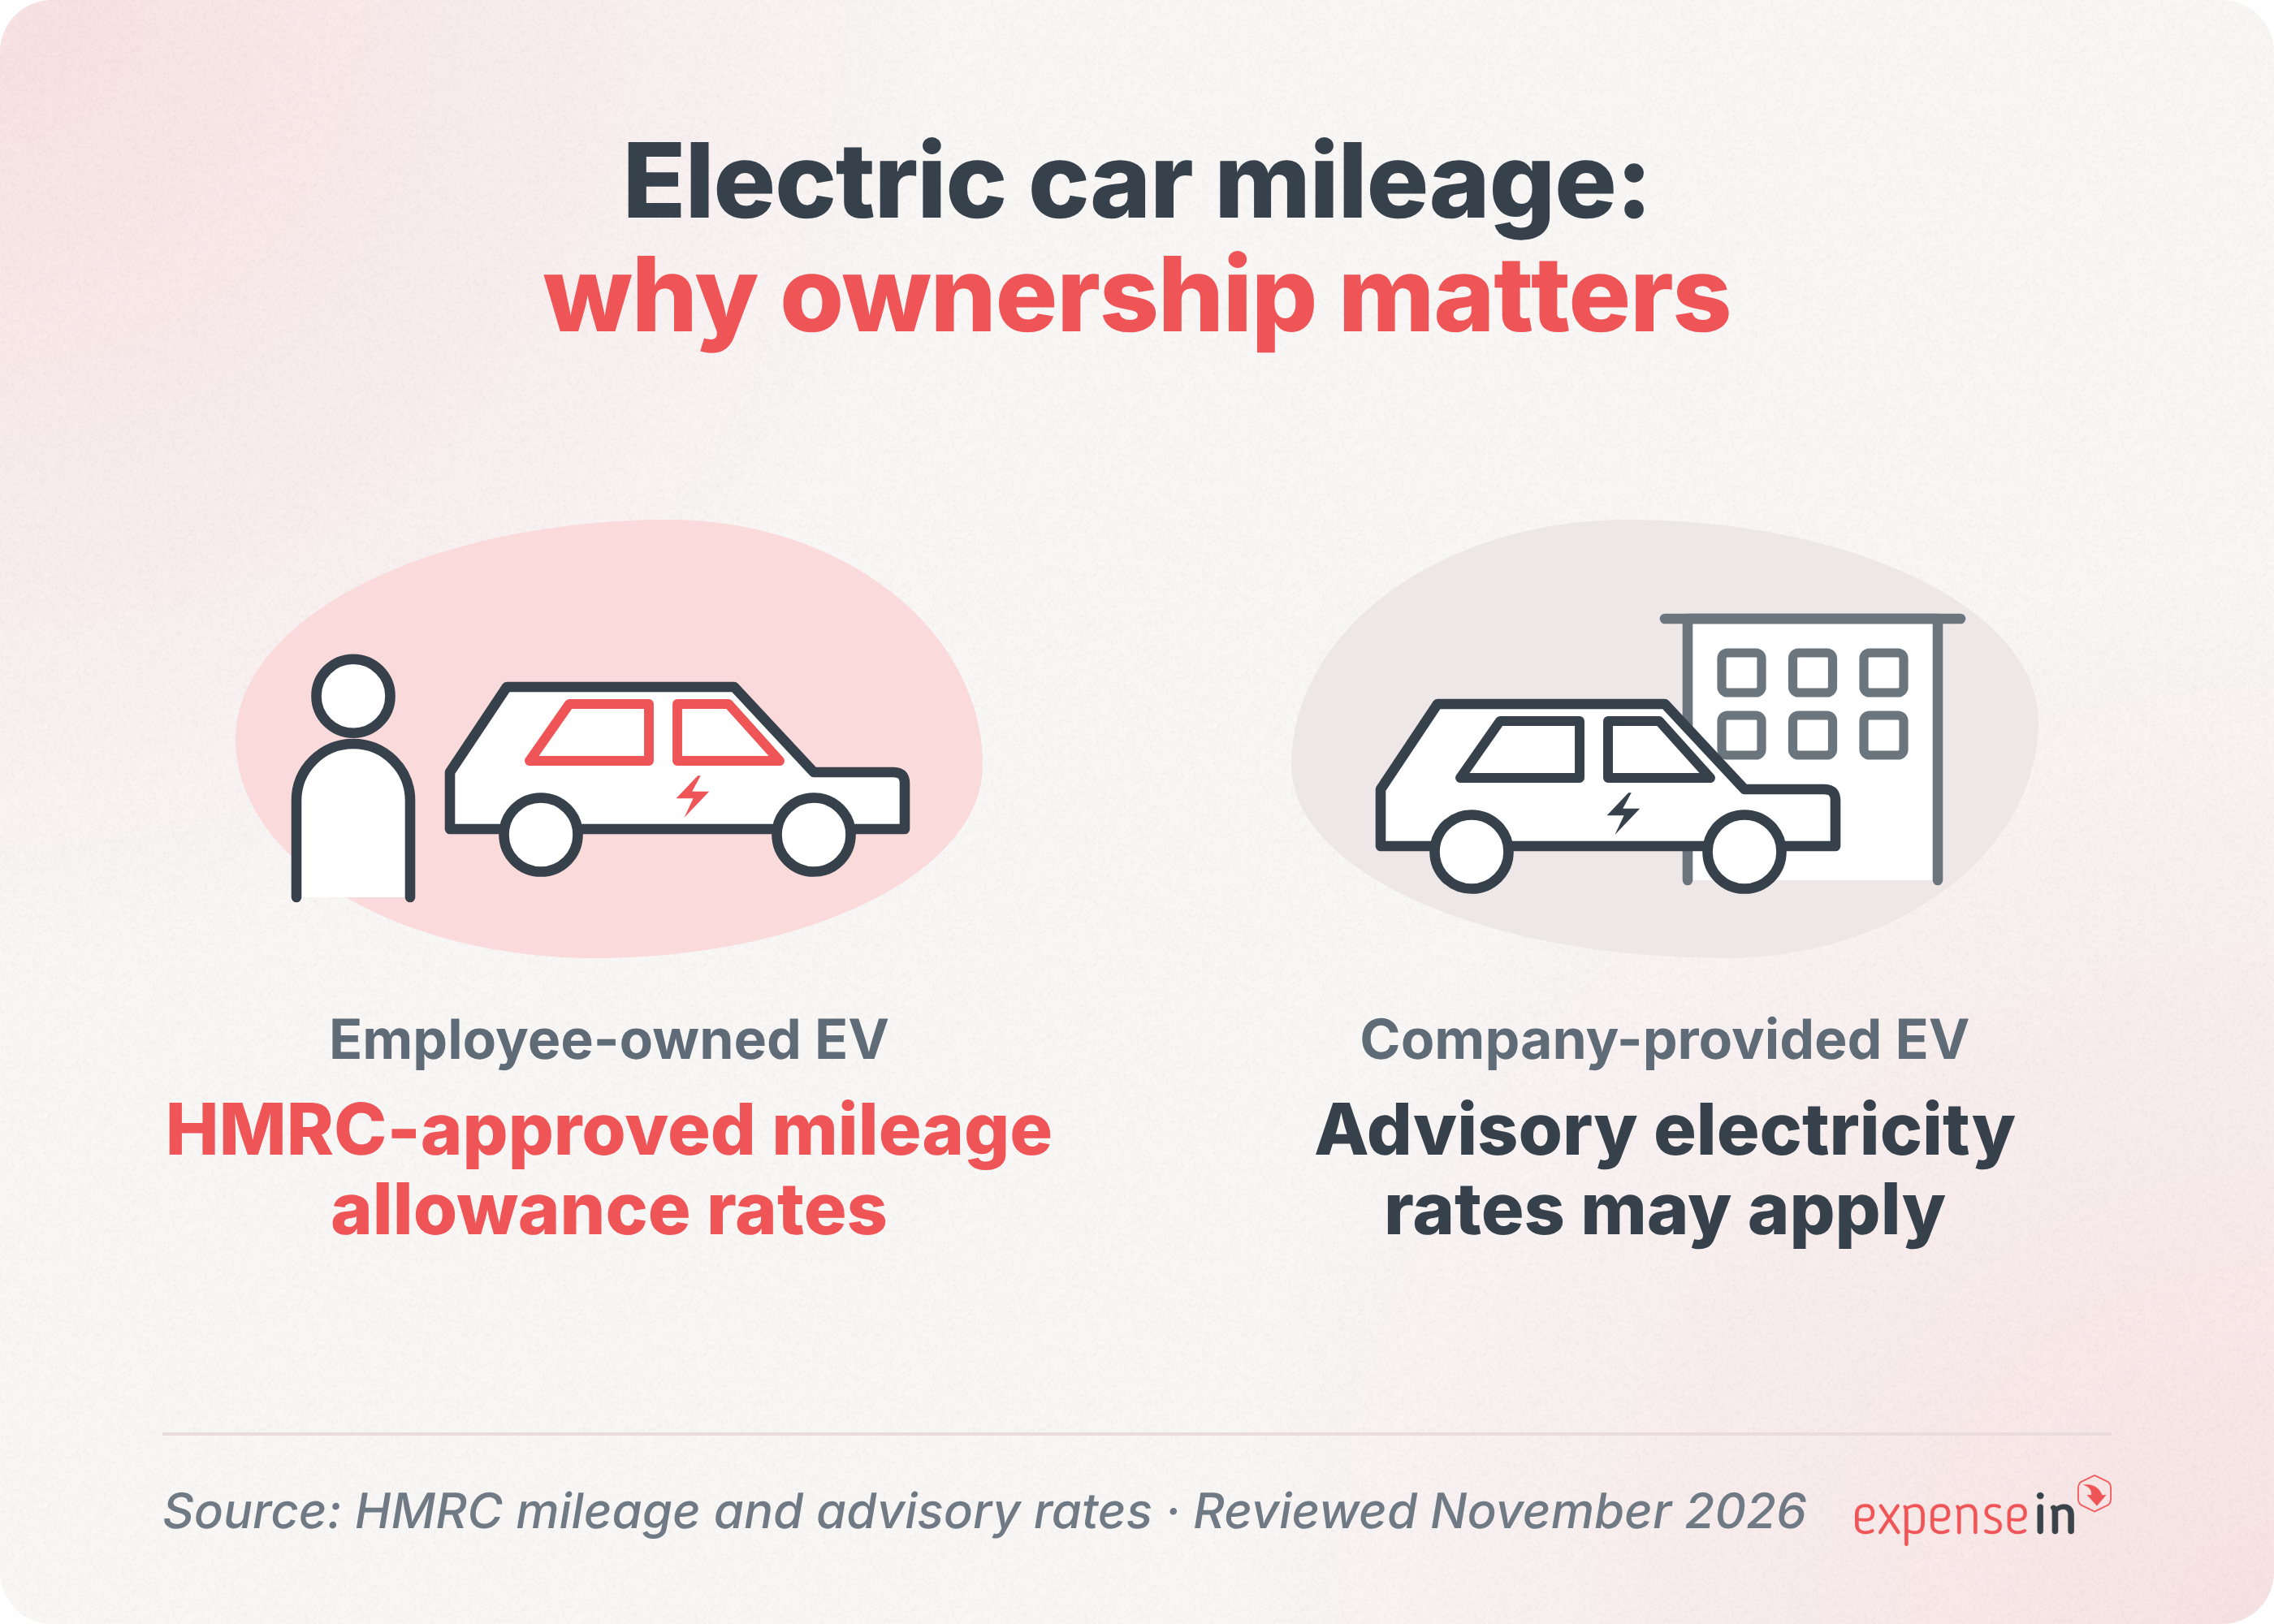
Employees using their own fully electric or hybrid cars for qualifying business journeys are covered by the same approved mileage allowance rates as other privately owned cars.
For 2026/27, that's:
55p per mile for the first 10,000 business miles
25p per mile for business mileage above 10,000
The rates cover the wider cost of owning and running the vehicle, not just the electricity or fuel used during a journey.
There isn't a separate, lower approved mileage allowance simply because an employee drives their own electric car.
Employees driving company electric cars
Company cars are treated differently.
Where employees drive a company-provided vehicle, HMRC's approved mileage allowance rates for personally owned vehicles don't apply in the same way.
Instead, employers can use HMRC's Advisory Fuel Rates (AFRs) and Advisory Electricity Rates (AERs) for relevant company car fuel or electricity reimbursements.
As of November 2026, the advisory electricity rates for fully electric company cars are:
Charging location | Advisory electricity rate |
|---|
Home charging | 7p per mile |
Public charging | 15p per mile |
These rates apply under the September 2026 schedule and remain unchanged in the rates published for 1 December 2026.
Where a company car is charged at a mixture of home and public charging locations, HMRC allows a fair and reasonable apportionment.
Petrol, diesel, and hybrid company cars have different advisory fuel rules. Rates vary according to factors such as fuel type and engine size.
Important: Advisory fuel rates are reviewed quarterly, so finance teams should check the latest schedule rather than relying on an outdated rate table.
Can businesses reclaim VAT on mileage expenses?
Potentially, yes. But VAT recovery on mileage isn't as simple as applying VAT to the entire reimbursement.
For VAT-registered businesses eligible to recover input tax, only the qualifying fuel element of a mileage allowance is relevant to a road-fuel VAT claim.
The wider allowance also covers items such as depreciation, insurance, and maintenance, which aren't treated as fuel expenditure.
To calculate the recoverable VAT, businesses need to establish the fuel element of the mileage payment using an acceptable method, such as relevant published fuel rates.
They must also maintain supporting records, including fuel invoices where required.
HMRC's guidance requires appropriate records showing:
Fuel invoices must support the relevant business fuel expenditure.
In practice, this means finance teams shouldn't simply calculate VAT on a full 55p-per-mile payment.
Electric vehicle charging has separate VAT considerations, so these road-fuel calculations should not automatically be applied to electricity reimbursements.
For businesses managing frequent claims, the quality of mileage records and supporting documents matters just as much as the rate being applied.
How should finance teams prepare for the 2027 mileage changes?
Mileage rates might look like a small part of expense management, but incorrect calculations can affect employee reimbursements, payroll reporting, and the records available when claims are reviewed.
Rather than simply changing one number in your expense policy, it's worth checking the full process.
Here are seven areas to review.
1. Check your current reimbursement rates
Start with the rates you're using today.
Are claims for 2026/27 being calculated using the correct approved allowances?
If you're still using the previous 45p rate, is that an intentional reimbursement policy or an outdated setting?
Not every business chooses to reimburse at the full approved rate, but employees should understand which policy applies.
2. Prepare for the April 2027 threshold change
Review how your business handles mileage above 10,000 miles.
The announced increase from 25p to 35p will matter most for employees with higher annual business mileage.
If your business intends to adopt the updated rates, plan when and how those changes will be applied once the legislation is in place.
3. Track cumulative mileage across the tax year
An employee's mileage threshold shouldn't reset every time they submit a claim.
Finance teams need an accurate record of qualifying business mileage over the tax year, including where employees use more than one car or van.
Without that information, it's easy to apply the wrong rate once someone crosses 10,000 miles.
4. Distinguish personal and company vehicles
Don't apply the same reimbursement rules to every driver.
Employees using their own cars, employees using company cars, and those driving fully electric company vehicles can fall under different arrangements.
Your mileage policy should make those distinctions clear.
5. Check which journeys are eligible
Make sure employees know what qualifies as business mileage.
Ordinary commuting, travel to temporary workplaces, hybrid working arrangements, and journeys between work locations may need different treatment.
This is particularly important for teams travelling between multiple sites or working on long-term assignments.
6. Review your payroll and VAT processes
Mileage payments can have different Income Tax, National Insurance, and VAT consequences.
Check how excess reimbursements are identified, how relevant payments are reported, and whether the records supporting fuel-related VAT claims are sufficient.
7. Make it easy to record and approve mileage
A clear policy works best when employees can follow it without complicated calculations or repeated clarification.
A practical mileage claim process should capture:
The date and business purpose of the journey
Start and end locations
Qualifying business miles travelled
Vehicle type and ownership
Applicable mileage rate
Supporting documents where required
Approval and payment details
These records give finance teams a clearer basis for reviewing claims and managing reimbursements.
Managing business mileage with ExpenseIn
Keeping mileage records accurate shouldn't mean checking every route manually or maintaining a separate spreadsheet for each employee.
ExpenseIn helps finance teams manage business travel from mileage tracking and approval through to reimbursement, all within one platform.
 With ExpenseIn, your team can:
Calculate mileage using Google Maps. Employees enter their journey details, and ExpenseIn calculates the distance, with the option to amend it where necessary.
Apply configured mileage rates. Set rates for personal and company car mileage, rather than asking employees to calculate every claim manually.
Track cumulative mileage. Monitor employee mileage across the tax year to help apply the correct rates as thresholds are reached.
Keep claim details together. Manage journey information, mileage calculations, supporting documents, and approvals in one place.
Calculate and report mileage VAT. Support VAT calculations on mileage claims using configured rates and maintain clearer records for finance.
Reimburse employees directly. With ExpenseIn Reimbursements, UK finance teams can include eligible, approved mileage claims in a payment run and pay employees without leaving ExpenseIn.
This gives finance teams a more consistent way to handle mileage claims, with clearer records and less manual calculation.
If you're reviewing your mileage policy ahead of April 2027, it's also worth checking whether your current processes are making claims and reimbursements harder to manage than they need to be.
 HMRC mileage rates: Frequently asked questions
For employees using their own cars or vans, the approved rate is 55p per mile for the first 10,000 qualifying business miles and 25p per mile thereafter. Motorcycle and bicycle rates are 24p and 20p per mile, respectively.
The government has announced that the rate for qualifying car and van business mileage above 10,000 miles will rise from 25p to 35p on 6 April 2027. Implementing legislation is still required as of this article's review date.
No. HMRC's approved mileage rates establish the amount employers can generally reimburse tax-free under the relevant rules. Businesses can set their own reimbursement rates, including lower rates.
Employees receiving less than the approved amount may be eligible for Mileage Allowance Relief.
Not when an employee uses their own electric car for qualifying business journeys.
The standard approved car mileage rates apply. Separate advisory electricity rates are relevant to qualifying reimbursements for company-provided electric cars.
Ordinary commuting between home and a permanent workplace generally doesn't qualify for tax-free mileage reimbursement.
Travel to a qualifying temporary workplace may be eligible, depending on the circumstances.
HMRC permits an additional tax-free passenger payment of up to 5p per mile for each fellow employee carried in a car or van, provided the journey is also qualifying business travel for the passenger.
There is no equivalent Mileage Allowance Relief if an employer pays less than this passenger rate.
Keep your mileage policy up to date
The latest HMRC mileage changes are a useful prompt to review how your business manages employee travel claims.
With the 55p rate now in effect and a further increase planned for April 2027, finance teams should make sure their reimbursement policies, calculations, and records reflect the correct tax-year rules.
A good mileage process isn't just about applying the right rate. It's about knowing which journeys qualify, keeping reliable records, and giving employees a straightforward way to submit claims.
ExpenseIn helps bring mileage recording, approvals, and reporting into one place, making day-to-day expense management easier for both employees and finance teams. Book a demo today.